An insured person discovered they were being charged fees that shouldn’t have been applied. He won his case and was able to get a refund. Other policyholders could be affected too.
NASA issues chilling warning: life on Earth won’t be possible after this date
This bizarre French customer habit is driving shop owners crazy
Insurance premiums for cars, homes, and health plans keep rising, and bills pile up every year. So when a few extra euros show up on a renewal notice, many people don’t dig into the reason. Yet some surcharges have no legal basis. One policyholder recently experienced this and the insurance ombudsman sided with him, according to UFC-Que Choisir.
Between coverages, taxes, and add-on charges, insurance pricing can be hard to untangle. Insurers have some discretion in setting rates, but that freedom isn’t unlimited. Certain increases are allowable, while others can be challenged—even if they’re written into the contract.
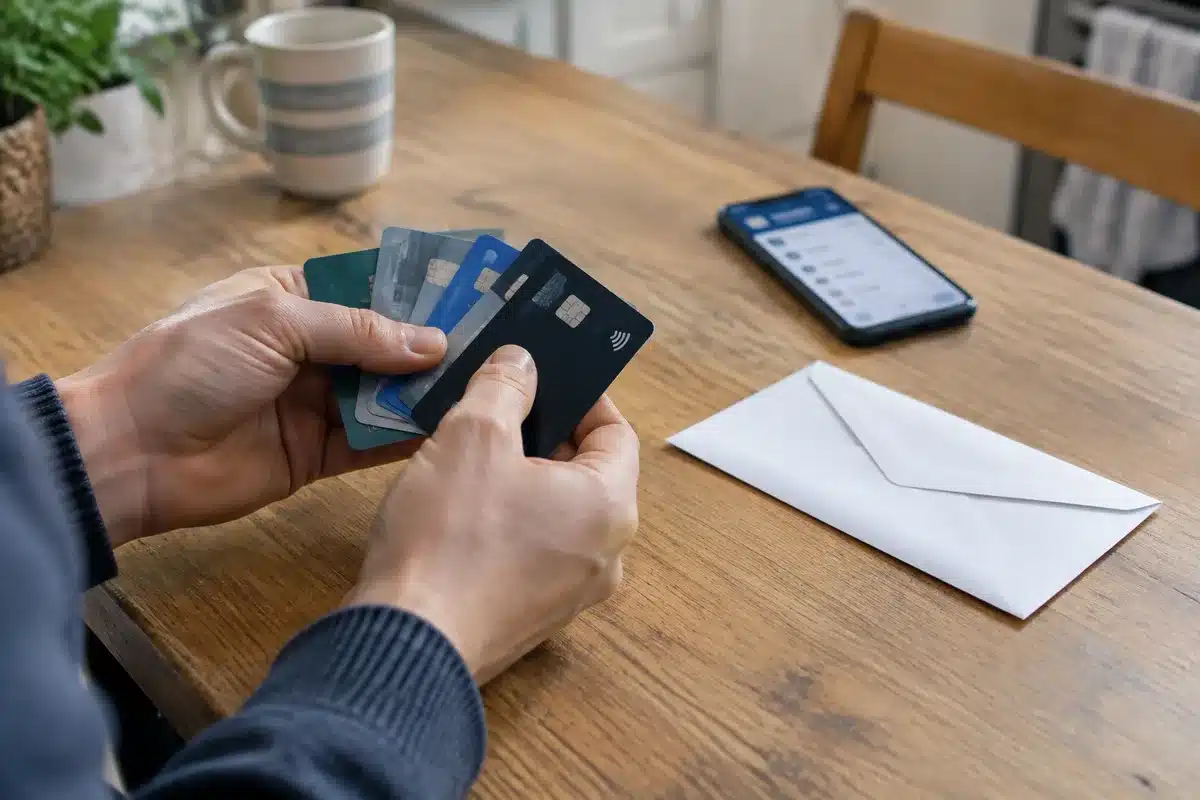
That’s exactly what happened in a case reviewed by the insurance ombudsman in a case study published October 6, 2026. The customer was being charged an extra 1% on all his policies because he refused automatic debit and paid by card or bank transfer instead. The issue: Article L. 112‑12 of the French Monetary and Financial Code prohibits businesses from adding surcharges based on the means of payment. The ombudsman therefore ordered the insurer to remove the surcharge and reimburse the amounts that had been wrongly charged.
Be careful not to confuse this with installment fees. An insurer may lawfully charge more if you opt to pay monthly rather than in a single annual payment; those fees can range from about 2% to 8% of the annual premium, UFC-Que Choisir notes. On a €600 policy, for example, that difference can reach €48. Another lawful approach is to give a genuine discount to customers who accept direct debit. Arnaud Chneiweiss, the insurance ombudsman, recommends favoring “an explicit discount for payment by direct debit rather than a surcharge applied to other means of payment,” he writes in the case study.
So how do you get your money back? Start by pulling your recent renewal notices and comparing amounts, especially if you pay by card or bank transfer. If you spot a surcharge tied to your payment method, ask your insurer in writing to justify it, and then demand that it be removed and that any improperly charged amounts be refunded, citing Article L. 112‑12. Keep copies of the renewal notices and all correspondence. If the insurer refuses or doesn’t give a satisfactory reply within two months of your written complaint, you can file a free complaint with the Insurance Mediation service.
Similar Posts
- Brazil’s PIX system is scaring Trump and Zuckerberg — here’s how
- You can withdraw cash without a card—here’s how it works!
- They won €205 million in EuroMillions… but will never see a cent of it
- Insurance Secrets Exposed: Essential Steps to Avoid Reimbursement Hassles Today!
- Even Small Transactions Must Be Card-Friendly, Merchants Can’t Refuse!

Felix Marlowe manages Belles and Gals’ vibrant social media platforms. With expertise in social engagement and viral marketing, Felix creates content that sparks conversation and keeps followers coming back for more. From celebrity news to trending challenges, Felix makes sure our social media stays at the forefront of pop culture.